Insurers Are Fleecing CA Employers: New Hampshire Edition
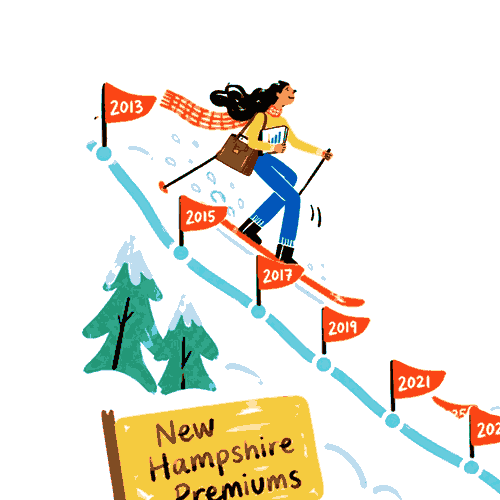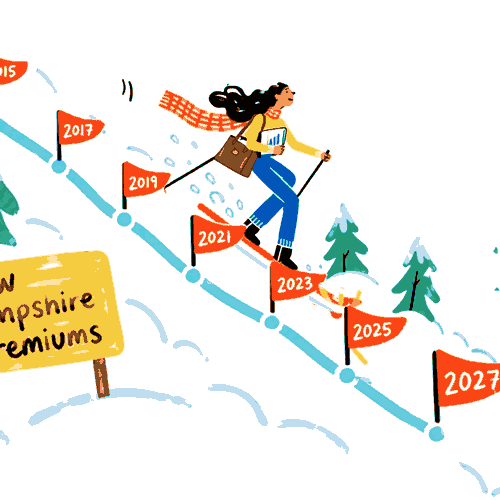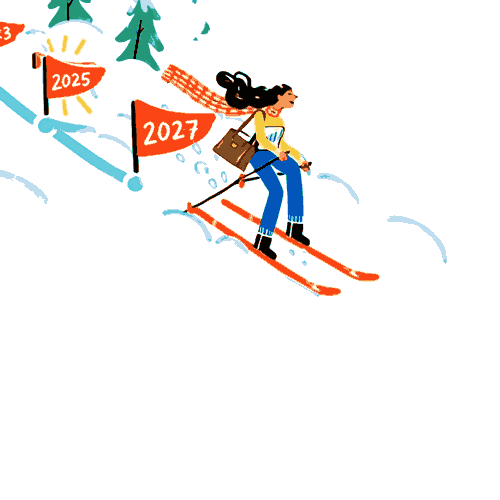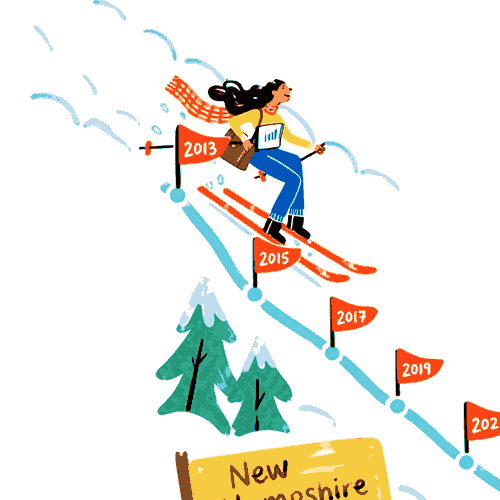
Employers in New Hampshire will pay less for workers’ comp coverage in 2027, as the Granite State joins most of the nation in lowering premium rates.
Effective January 1, the New Hampshire Insurance Department (NHID) approved a 2.9% cut to loss costs for the voluntary market and a 3.4% cut for the assigned risk pool. This follows last year’s respective 6.1% and 5.4% reductions and marks the 15th consecutive decrease.
Loss costs, which directly inform premium rates, have reportedly dropped cumulatively by 68% in New Hampshire since the streak began.
Regular readers will know how this news should sit with employers in California, whose premiums are rising. With the fourth-highest rates nationally, unimpressive medical inflation, and relatively cheap provider reimbursement rates, it’s hard to fathom why California continues to accede to insurers’ demands for more money.
NCCI Keeps the Cuts Coming
The NHID takes its cues from the National Council on Compensation Insurance (NCCI), which formally advises the majority of states on loss costs.
Insurance Commissioner D.J. Bettencourt was jubilant in an NHID press release, asserting that easing the burden on employers is not in conflict with ensuring that injured workers get the care and benefits to which they’re entitled. According to Bettencourt, a well-functioning comp market can do both (emphases ours):
“It is a good example of what a healthy insurance market should accomplish: competition, disciplined risk management, and workplace safety working together to lower costs without compromising protection for injured workers.”
According to the NHID, the 15-year streak of NCCI-induced loss cost decreases amounts to a cumulative drop of 68%. Consequently, employers in 2027 will pay significantly less to cover their injured employees than they did in the previous decade, when the trend began.
CA Avoids the Difficult Conversations
California has saddled employers with consecutive premium increases, largely on the advice of the Workers’ Compensation Insurance Rating Bureau (WCIRB), an insurer-funded group credibly accused of “skewing” data to the benefit of its members.
As daisyNews will never stop saying until we hear a sufficient response, the WCIRB’s justifications are questionable at best.
The WCIRB and other payer-friendly observers point to Cumulative Trauma claims and “unlisted” medical services as convenient culprits, without proving their case with hard data (which would be impossible, since a lack of comprehensive data precludes any objective studies of the system).
Meanwhile, even the WCIRB acknowledges that administrative expenses eat up $0.52 for every dollar of care and benefits delivered, and the Workers’ Compensation Research Institute found that spending on measures like networks, discount contracting, litigation, and Medical-Legal services are 46% above the median state studied.
In other words, medical care and benefits are not the logical place to look for wasteful comp spending.
Comp outperforms most other lines of insurance nationally. California’s fee schedules are low and subject to rampant discounting. Loss ratio data strongly suggest that insurers in California are doing well, as do major dividend payouts from the state’s non-profit insurer of last resort.
So we’ll keep asking: what are California employers paying for?
daisyBill is connected directly to each clearinghouse, so your e-bills get delivered (and paid) quickly. Click below to learn more:
BILL BETTER: DAISYBILL
DaisyBill provides content as an insightful service to its readers and clients. It does not offer legal advice and cannot guarantee the accuracy or suitability of its content for a particular purpose.